Penn Mutual Whole Life Insurance Review (2026)
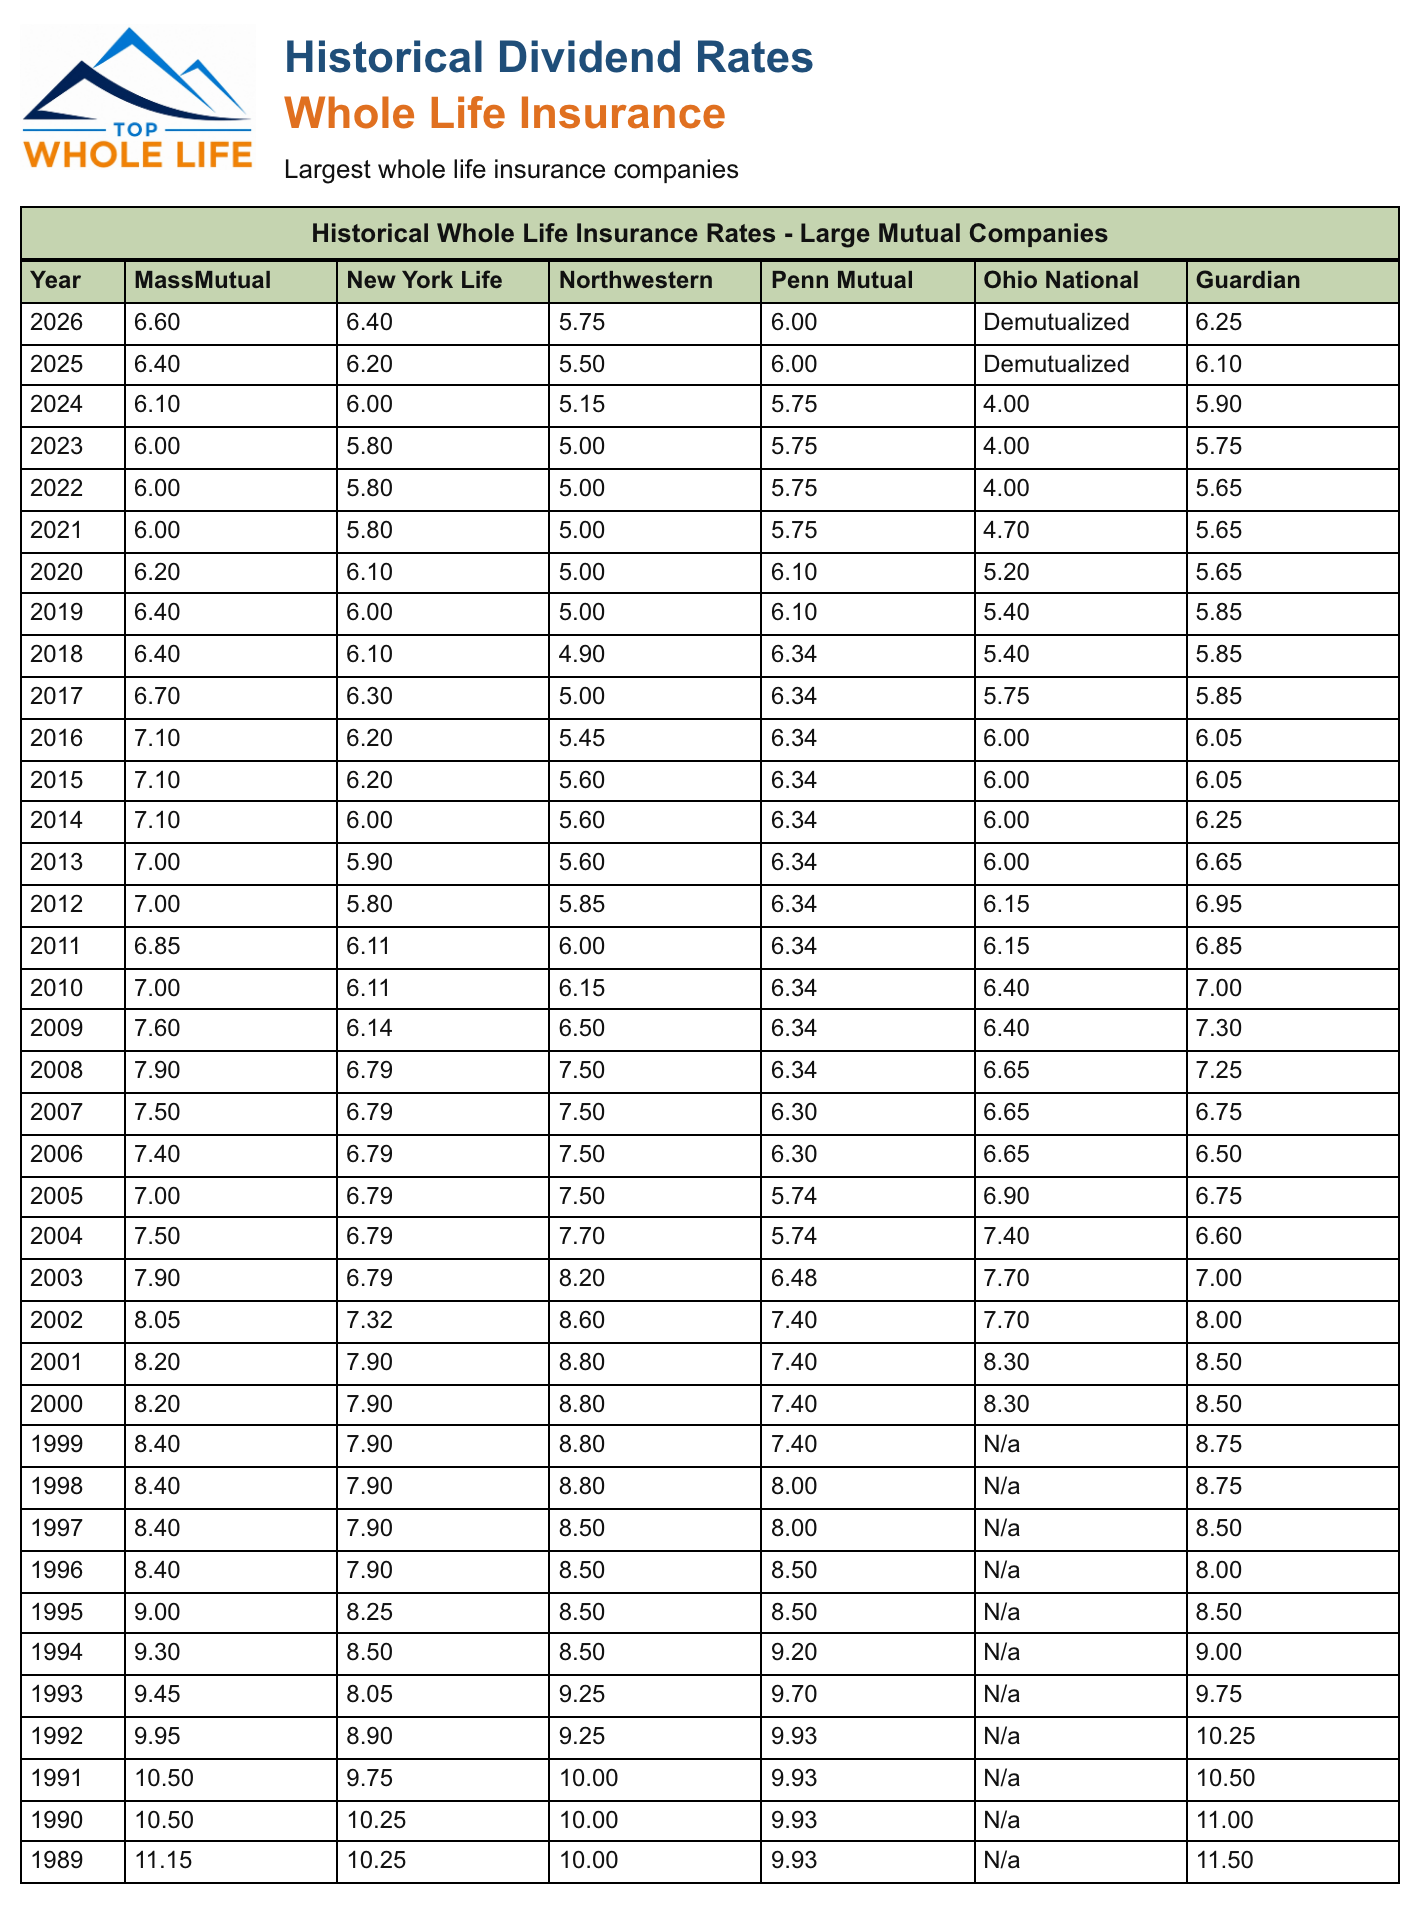
2026 verdict: Penn Mutual is a smaller mutual that still illustrates among the top cash-value designs. The 2026 dividend interest rate is 6.00% (flat vs. 2025). A.M. Best is A+, a step below MassMutual and New York Life’s A++. If the job is maximum illustrated cash value or flexible limited-pay, Penn Mutual belongs in the first three quotes — not as a brand-name default.
Who it is for
Buyers who want participating whole life, a long dividend record (since 1847), and a company that independent agents can actually place. Compare it on the same design to MassMutual before you decide.
Skip or deprioritize if you only want the highest financial-strength stack (A++) or an easy online self-serve quote from the carrier.
Strengths
- Participating whole life with a stable recent DIR
- Flexible pay periods (including short limited-pay)
- Independent-agent access
- Competitive illustrated cash value on many ages
Weaknesses
- A+ / AA− is strong, not the A++ club
- DIR sat at 5.75% for 2021–2023 after a long 6.34% run
- No useful carrier-direct online quote — use a broker illustration
Ratings
| Agency | Rating |
|---|---|
| A.M. Best | A+ (Superior) |
| Moody's | Aa3 (Excellent) |
| S&P | AA− |
Founded in 1847. Current assets and surplus change every year — use Penn Mutual’s company site for the latest statutory package, not a 2021 screenshot.
Dividend
Penn Mutual held 6.34% for many years, then stepped down (2019 and 2021). 2024–2026 printed 6.00%. That is not a “drop” in 2026 — it is a hold. Year-by-year rates: whole life dividend rate history.
Penn Mutual is direct recognition on loans: borrowed cash value generally stops earning the full dividend. Non-direct-recognition companies credit as if the money were still in the policy (and charge a loan rate from the general account). Neither is automatically better. If you plan to borrow, illustrate both Penn Mutual and a non-direct peer such as New York Life.
Products
Penn Mutual also sells term, universal life, and disability. Whole life is the reason to be here.
Guaranteed Choice Whole Life — traditional guarantees plus flexible pay (short limited-pay through pay-to-100/121). Participating. Related: limited pay whole life insurance.
Versatile Choice Whole Life — design-your-pay-period. Common riders: overloan protection, waiver of premium, chronic-illness acceleration.
Survivorship Choice Whole Life — second-to-die for estate taxes and legacy, not first-death income replacement.
IUL is a different product. If that is the question, start at whole life vs indexed universal life — do not buy IUL because a whole life illustration looked good.
Underwriting classes
Preferred Best (some term), Preferred Plus Non-Tobacco, Preferred Non-Tobacco, Standard Non-Tobacco, Preferred Tobacco, Standard Tobacco. Issue ages 0–19 are typically standard only.
Bottom line
Penn Mutual is a keep-and-compare mutual, not a household brand. Rank it on top whole life companies for cash value against MassMutual, New York Life, and Guardian. Ohio National is no longer a current participating pick after demutualization — see the Ohio National review only if you already own a policy.
Top Whole Life is independent. We do not work for Penn Mutual.