Limited Pay Life Insurance Policy (2026): 10-Pay vs 20-Pay
Updated October 17, 2026.
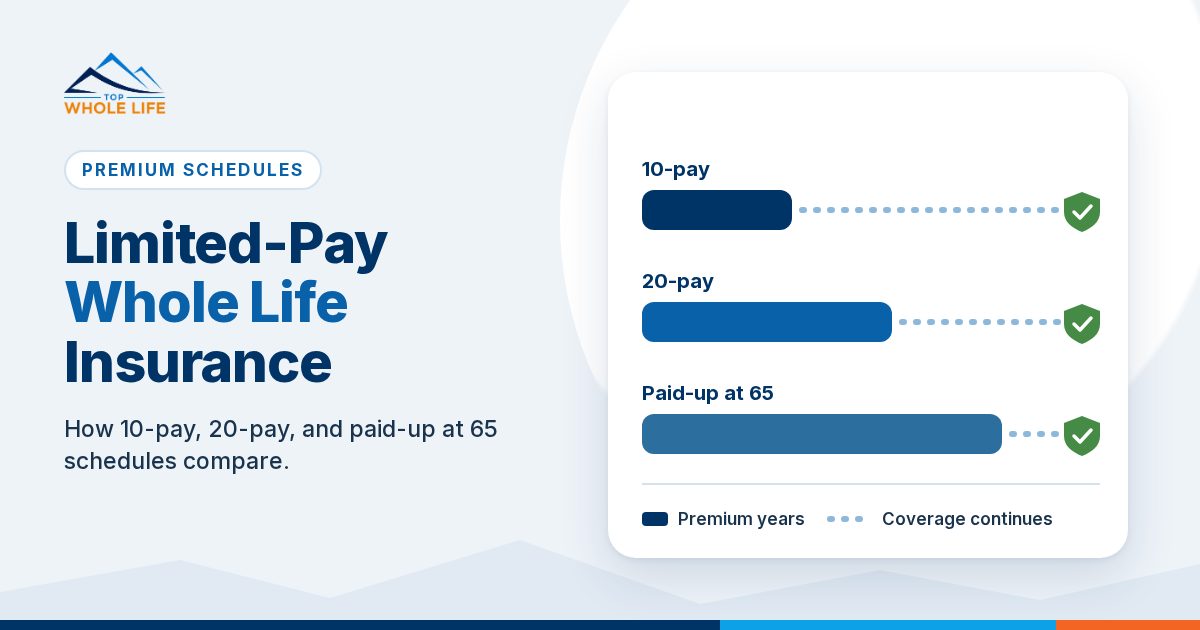
A limited pay life insurance policy is limited-payment whole life insurance. You pay required premiums for a shorter period than on ordinary lifetime-pay whole life. After those contractual premiums are paid, the coverage is designed to last for life without further premiums. The schedules state insurance departments use as examples are a 10-pay, a 20-pay, and paid-up at 65.
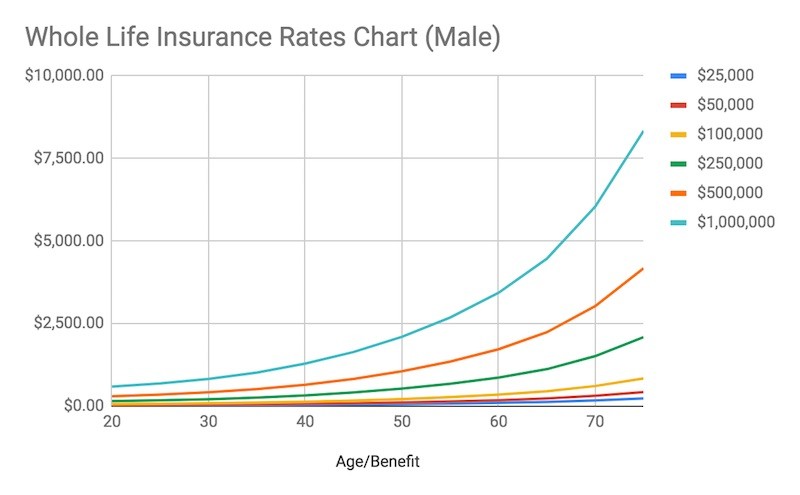
The annual premium is higher than on lifetime-pay whole life because the same kind of coverage is funded over fewer years. Assurity publishes one consumer illustration, and Policygenius publishes a dated MassMutual illustration. The dollars do not match, so each quote is labeled on its own. They are not a price for every buyer. For how age, health, and face amount change a premium, see how much whole life insurance costs. For a personal illustration, use the whole life quote form.
What a limited pay life insurance policy is
As of October 17, 2026, the NAIC life insurance topic page (last updated November 14, 2025) and the New York Department of Financial Services consumer FAQ describe the same contract. Premiums are paid over a shorter time than on an ordinary lifetime-pay whole life policy, and the protection is still meant to last for life. New York’s FAQ names the common shapes: a set number of years, such as 10-payment or 20-payment whole life, or an age, such as paid up at 65 or at 85.
The Ohio Department of Insurance life and annuity guide says some whole life policies let you pay premiums for a shorter period, such as 20 years or until age 65, and that those premiums are higher because they are paid over a shorter period. The Washington Office of the Insurance Commissioner says whole life sometimes lets you pay for a shorter time, such as 15 years or until age 65, and that the premiums are higher because you pay them over a short time.
Paid up means the contractual premium-paying period is finished. Stopping early is a different result. If premiums stop before the policy is paid up, state law requires a nonforfeiture value, paid in cash or as some other form of insurance (NAIC). New York’s FAQ says that if you stop paying you can take the cash value or use it to provide a paid-up insurance benefit, and that the company must provide either extended term insurance or reduced paid-up coverage.
Single-premium whole life is also a limited-payment policy: one premium at issue, and then no further premiums (NAIC; New York DFS). The comparison below is the three scheduled designs, not a single premium.
10-pay, 20-pay, and paid-up at 65
As of Oct 17, 2026. The departments agree that a shorter premium-paying period means a higher annual premium than a longer one, on a comparable whole life policy. They do not publish one shared dollar. The two example quotes below use different carriers, sexes, face amounts, and dates, so they are not averaged and they are not a range.
| Schedule | Premiums required | Annual premium vs a longer pay | Paid up |
|---|---|---|---|
| 10-pay | 10 years | Higher than a 20-pay and higher than lifetime-pay on a comparable policy | After the 10 premiums are paid |
| 20-pay | 20 years | Lower than a 10-pay and higher than lifetime-pay on a comparable policy | After the 20 premiums are paid |
| Paid-up at 65 | Until age 65 | Depends on how many years are left until 65 | At 65, if those premiums were paid |
New York’s FAQ is the source that names all three rows. The Ohio guide names 20 years and age 65. Washington’s insurance commissioner names a shorter period that can run to age 65. Paid-up at 65 is not a fixed number of years, so its premium is not ranked against a 10-pay without an issue age.
Assurity example quote
Checked as of Oct 17, 2026. Assurity’s limited-pay flyer (form 15-834-011001-25) shows one illustration: female, age 40, Preferred Plus non-tobacco, $75,000 face, monthly premium. Assurity says the product is not available in New York, and that rates may vary by state.
| Schedule | Monthly premium |
|---|---|
| 10-pay | $173.15 |
| 20-pay | $104.44 |
| Paid-up at 65 | $89.70 |
MassMutual example quote, via Policygenius
Checked as of Oct 17, 2026. Policygenius (page updated March 1, 2024) publishes sample monthly rates for MassMutual limited-pay whole life. Policygenius dates that illustration January 1, 2024. The row below is male, age 40, Preferred Plus non-smoker, $500,000 face, monthly premium. Policygenius says the rates may vary by insurer, coverage amount, health class, and state, and that not every policy is available in every state.
| Schedule | Monthly premium |
|---|---|
| 10-pay | $2,829 |
| 20-pay | $1,247 |
| Paid-up at 65 | $1,074 |
One current product list, so the names are not only from the consumer guides: on October 6, 2026, MassMutual said its whole life series includes Whole Life Guard 10 Pay and Whole Life 8/10/15/20 Pay, along with other contracts. MassMutual also said the products, or certain features, may not be available in every state (MassMutual press release, October 6, 2026). That is one company’s list. It is not a premium.
Traditional whole life scheduled premiums are generally level for the period the contract requires (New York DFS; Ohio guide). Limited-payment policies can be participating or nonparticipating (NAIC). On a participating policy, dividends are not guaranteed (New York DFS; Ohio guide). Carrier dividend history is kept on the dividend rate history page.
Pros and cons
As of October 17, 2026.
Pros
- Lifetime protection with a contractual end date for required premiums, once those premiums have been paid (New York DFS; NAIC).
- A generally level scheduled premium during the paying period (New York DFS; Ohio guide).
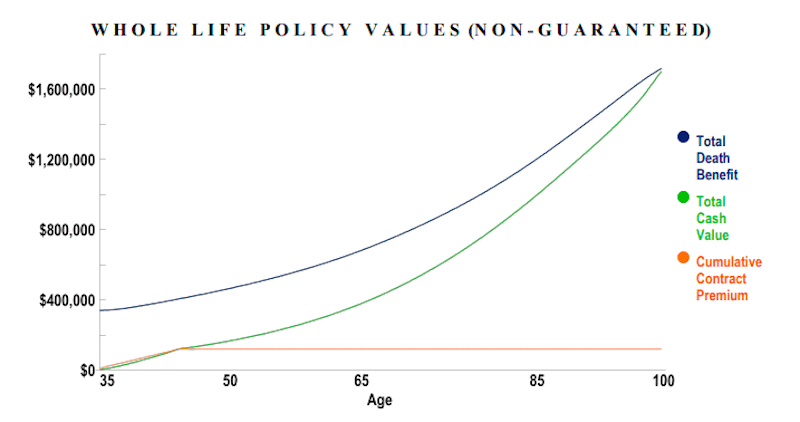
- Cash value is part of whole life. The NAIC says that cash value grows without being taxed as it builds. New York’s FAQ says the interest build-up inside the annual increase in cash value is not taxed annually under the Internal Revenue Code, and that the cash value grows tax-deferred.
- Death proceeds paid because the insured died are generally not included in the beneficiary’s gross income. The IRS life insurance proceeds FAQ (last reviewed October 11, 2026) and Publication 554 (2025) both say that. Both also say interest paid on the proceeds can be taxable, and both limit the exclusion when the policy was transferred for a price. New York’s FAQ agrees that death proceeds are typically not subject to income tax.
Cons
- The annual premium is higher than ordinary lifetime-pay whole life because the paying period is shorter (NAIC; New York DFS; Ohio guide; Washington OIC).
- Whole life already costs more at the start than the same death benefit bought as term (New York DFS). A limited-pay schedule raises the annual whole life premium further.
- Stopping early replaces the original death benefit with a nonforfeiture value (NAIC; New York DFS).
- If you surrender the policy for cash, the amount above your cost in the contract is generally taxable. Publication 554 describes that cost as premiums you paid, minus refunded premiums, rebates, dividends, and unrepaid loans that were not already included in your income. New York’s FAQ states the same result: only the excess of the cash value over premiums paid, less dividends, is taxable.
- Dividends are not guaranteed. Using them to pay later premiums is optional on a participating policy, and the result can change (New York DFS; Ohio guide).
You may be able to borrow against cash value. The NAIC and New York’s FAQ both say a whole life policyholder may borrow against it. The loan terms sit in the contract. This page does not quote a loan interest rate. The sources do not agree on one number.
Who a limited-payment schedule fits
This is a fit test based on the premium mechanics above. It is not a rate class and not a personal recommendation.
A limited-payment schedule fits someone who wants lifetime coverage and can pay the higher annual premium through a date they can name.
- 10-pay fits a buyer who can fund ten higher annual premiums and wants the contractual paying period to be ten years.
- 20-pay fits a buyer who wants the schedule to end twenty years after issue. A buyer who starts a 20-pay in their thirties finishes that premium schedule in their fifties. The annual premium is lower than a 10-pay on a comparable policy, and still higher than lifetime-pay whole life.
- Paid-up at 65 fits a buyer who wants required premiums to stop at 65. Bought younger, the annual premium is spread over more years. Bought close to 65, the window is short, so the annual premium is higher.
It fits poorly when the higher premium is not payable every year of the schedule. An early lapse replaces the original death benefit with a nonforfeiture option. It also fits poorly when the job is the lowest premium for a temporary need. Term starts out cheaper for that job (New York DFS). Lifetime-pay whole life is the lower annual premium when you want whole life and you are willing to keep paying.
If cash value is the reason you are comparing short pay periods, start with the cash-value company list and then ask for the same face amount on a 10-pay, a 20-pay, and a paid-up-at-65 design. One illustration is not the market.
Paid up by contract, and a premium picture that uses dividends
As of October 17, 2026. New York’s FAQ says dividends, while not guaranteed, may be used to pay some or all of the scheduled premiums if you choose that. An illustration can then show a later outlay of zero on a policy that still has a contractual premium.
The NAIC Life Insurance Illustrations Model Regulation says an illustration shall not use “vanish” or “vanishing premium,” or a similar term that implies the policy becomes paid up, to describe a plan for using non-guaranteed elements to pay a portion of future premiums. Iowa’s version of that rule, 191—14.6, effective April 24, 2024, uses the same prohibition. On a limited-pay whole life policy, required premiums end because the contract says so.
Universal life is a separate pattern. The NAIC describes it as permanent coverage where the premium and the death benefit can change, and the policy stays in force while the cash value is enough to cover insurance costs. Washington’s insurance commissioner calls universal life flexible-premium adjustable life. A universal life illustration that shows premiums stopping is not a 10-pay or 20-pay whole life contract. The longer comparison is whole life versus universal life.
The Ohio guide says the company should show you the benefits that are not guaranteed and what the company guarantees. Read both pictures before you treat a later year of zero outlay as a fact.
What to check before you buy
Ask for three illustrations on the same insured and the same face amount: 10-pay, 20-pay, and paid-up at 65. On each one, read the year required premiums contractually stop, the guaranteed column, and the non-guaranteed column. If the policy stays in force only on the non-guaranteed picture, you are looking at a dividend or crediting assumption.
What whole life insurance is is the shorter primer if the product itself is new. Request the three designs on the whole life quote form.
What is a limited pay life insurance policy?
A limited pay life insurance policy is limited-payment whole life. Required premiums run for a shorter period than on ordinary lifetime-pay whole life, and the coverage is designed to last for life after that period is completed. As of October 17, 2026, the NAIC and the New York Department of Financial Services describe it that way. The annual premium is higher because the paying period is shorter.
What is limited-payment whole life insurance?
It is the same contract type. “Limited-payment whole life” is the name on the NAIC topic page and in the New York DFS FAQ. “Limited pay life insurance policy” is the same idea: a 10-pay, a 20-pay, or a policy paid up at an age such as 65.
How is a 10-pay different from a 20-pay?
Both are limited-payment whole life. A 10-pay requires premiums for 10 years. A 20-pay requires them for 20 years. New York’s FAQ names both. On a comparable policy, the 10-pay has the higher annual premium because its paying period is shorter. After the stated premiums are paid, further premiums are not required.
What does paid-up at 65 mean?
Required premiums run until age 65. New York’s FAQ, the Ohio guide, and Washington’s insurance commissioner all describe a whole life policy that can be paid up at 65. The annual premium depends on how many years remain until 65 when you buy it.
Is the annual premium lower than lifetime-pay whole life?
The annual premium is higher. The NAIC, New York DFS, the Ohio guide, and Washington’s insurance commissioner all tie that higher premium to the shorter paying period. What gets shorter is the number of years you pay.
Does the death benefit continue after the premiums stop?
It is designed to continue after the contractual premiums have been paid and the policy is paid up. That is the NAIC and New York DFS description of limited-payment whole life. If premiums stop before the policy is paid up, the result is a nonforfeiture value, in cash or as other insurance.
Are death proceeds and cash value taxed?
Death proceeds paid because the insured died are generally not income to the beneficiary, as of the IRS FAQ last reviewed October 11, 2026, and Publication 554 (2025). Interest on those proceeds can be taxable, and a transfer of the policy for a price can limit the exclusion. Cash value inside the policy is not taxed annually as it builds, according to the NAIC and New York’s FAQ. If you surrender the policy, the amount above your cost is generally taxable. This is general information, not tax advice for one contract.
Is limited-pay the same as a vanishing premium?
A limited-pay policy ends required premiums because the contract sets that end date. A picture that uses dividends to pay later premiums is a different arrangement. The NAIC illustration model and Iowa’s illustration rule, effective April 24, 2024, both bar using “vanish” or “vanishing premium” to imply that a plan using non-guaranteed elements is paid up.
Sources checked October 17, 2026
- NAIC, Life Insurance, topic page last updated November 14, 2025.
- New York DFS, Consumer Life Insurance FAQ, fetched October 17, 2026.
- Ohio Department of Insurance, Life and Annuity Insurance Guide, fetched October 17, 2026.
- Washington Office of the Insurance Commissioner, Types of cash value life insurance, fetched October 17, 2026.
- MassMutual press release, October 6, 2026. Product names only. No premium from this release is used above.
- Policygenius, Limited pay life insurance, page updated March 1, 2024. MassMutual sample monthly rates, illustration valid as of January 1, 2024. Checked October 17, 2026.
- Assurity limited-pay flyer, form 15-834-011001-25. Checked October 17, 2026.
- IRS, Life insurance proceeds FAQ, page last reviewed October 11, 2026.
- IRS Publication 554 (2025), Life Insurance Proceeds and surrender gain.
- NAIC Life Insurance Illustrations Model Regulation (Model 582).
- Iowa Administrative Code 191.14, effective April 24, 2024.