MassMutual Whole Life Insurance Review (2026)
2026 verdict: MassMutual is still the first mutual we illustrate for cash-value whole life. The 2026 dividend interest rate is 6.60% — the highest published rate among the large mutuals — on a record $2.9 billion payout. Financial strength is A++. The highest DIR is not automatically the best illustration versus Penn Mutual or New York Life. Compare the same pay period before you buy.
Overview
MassMutual (Massachusetts Mutual Life Insurance Company) has been a mutual since 1851. It has not missed a dividend payment in the modern record. Whole life is the core product. Term (Vantage) is the conversion bridge. Coverpath was an online apply path — see the Coverpath by MassMutual review. The public Coverpath URL now redirects to a login dashboard, not a new-business quote.
On our top whole life companies for cash value and how much whole life insurance costs pages, MassMutual is usually #1 or #2. That is illustration performance, not a promise.
Company strength
| Agency | Rating |
|---|---|
| A.M. Best | A++ (Superior) |
| Fitch | AA+ (Very Strong) |
| Moody's | Aa3 (Excellent) |
| S&P | AA+ (Very Strong) |
MassMutual ranks #100 on the 2026 Fortune 500 (175th anniversary year). The company reports more than $1 trillion of life insurance in force. Current figures live on MassMutual's financial summary.
Dividend
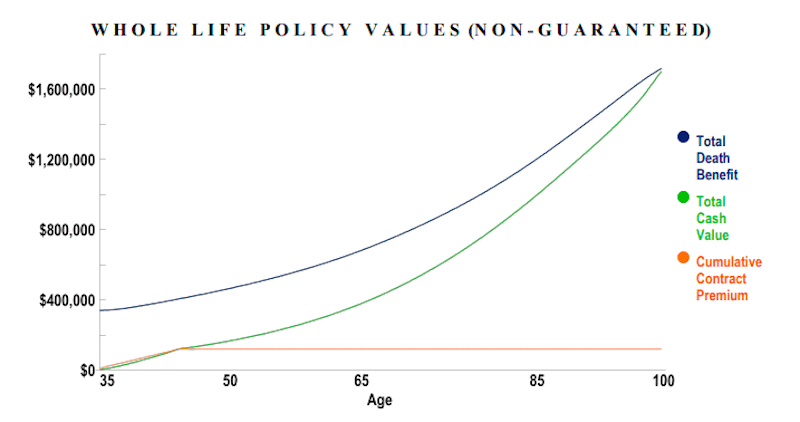
Participating whole life pays a dividend on top of guarantees when the board declares one. Dividends are not guaranteed.
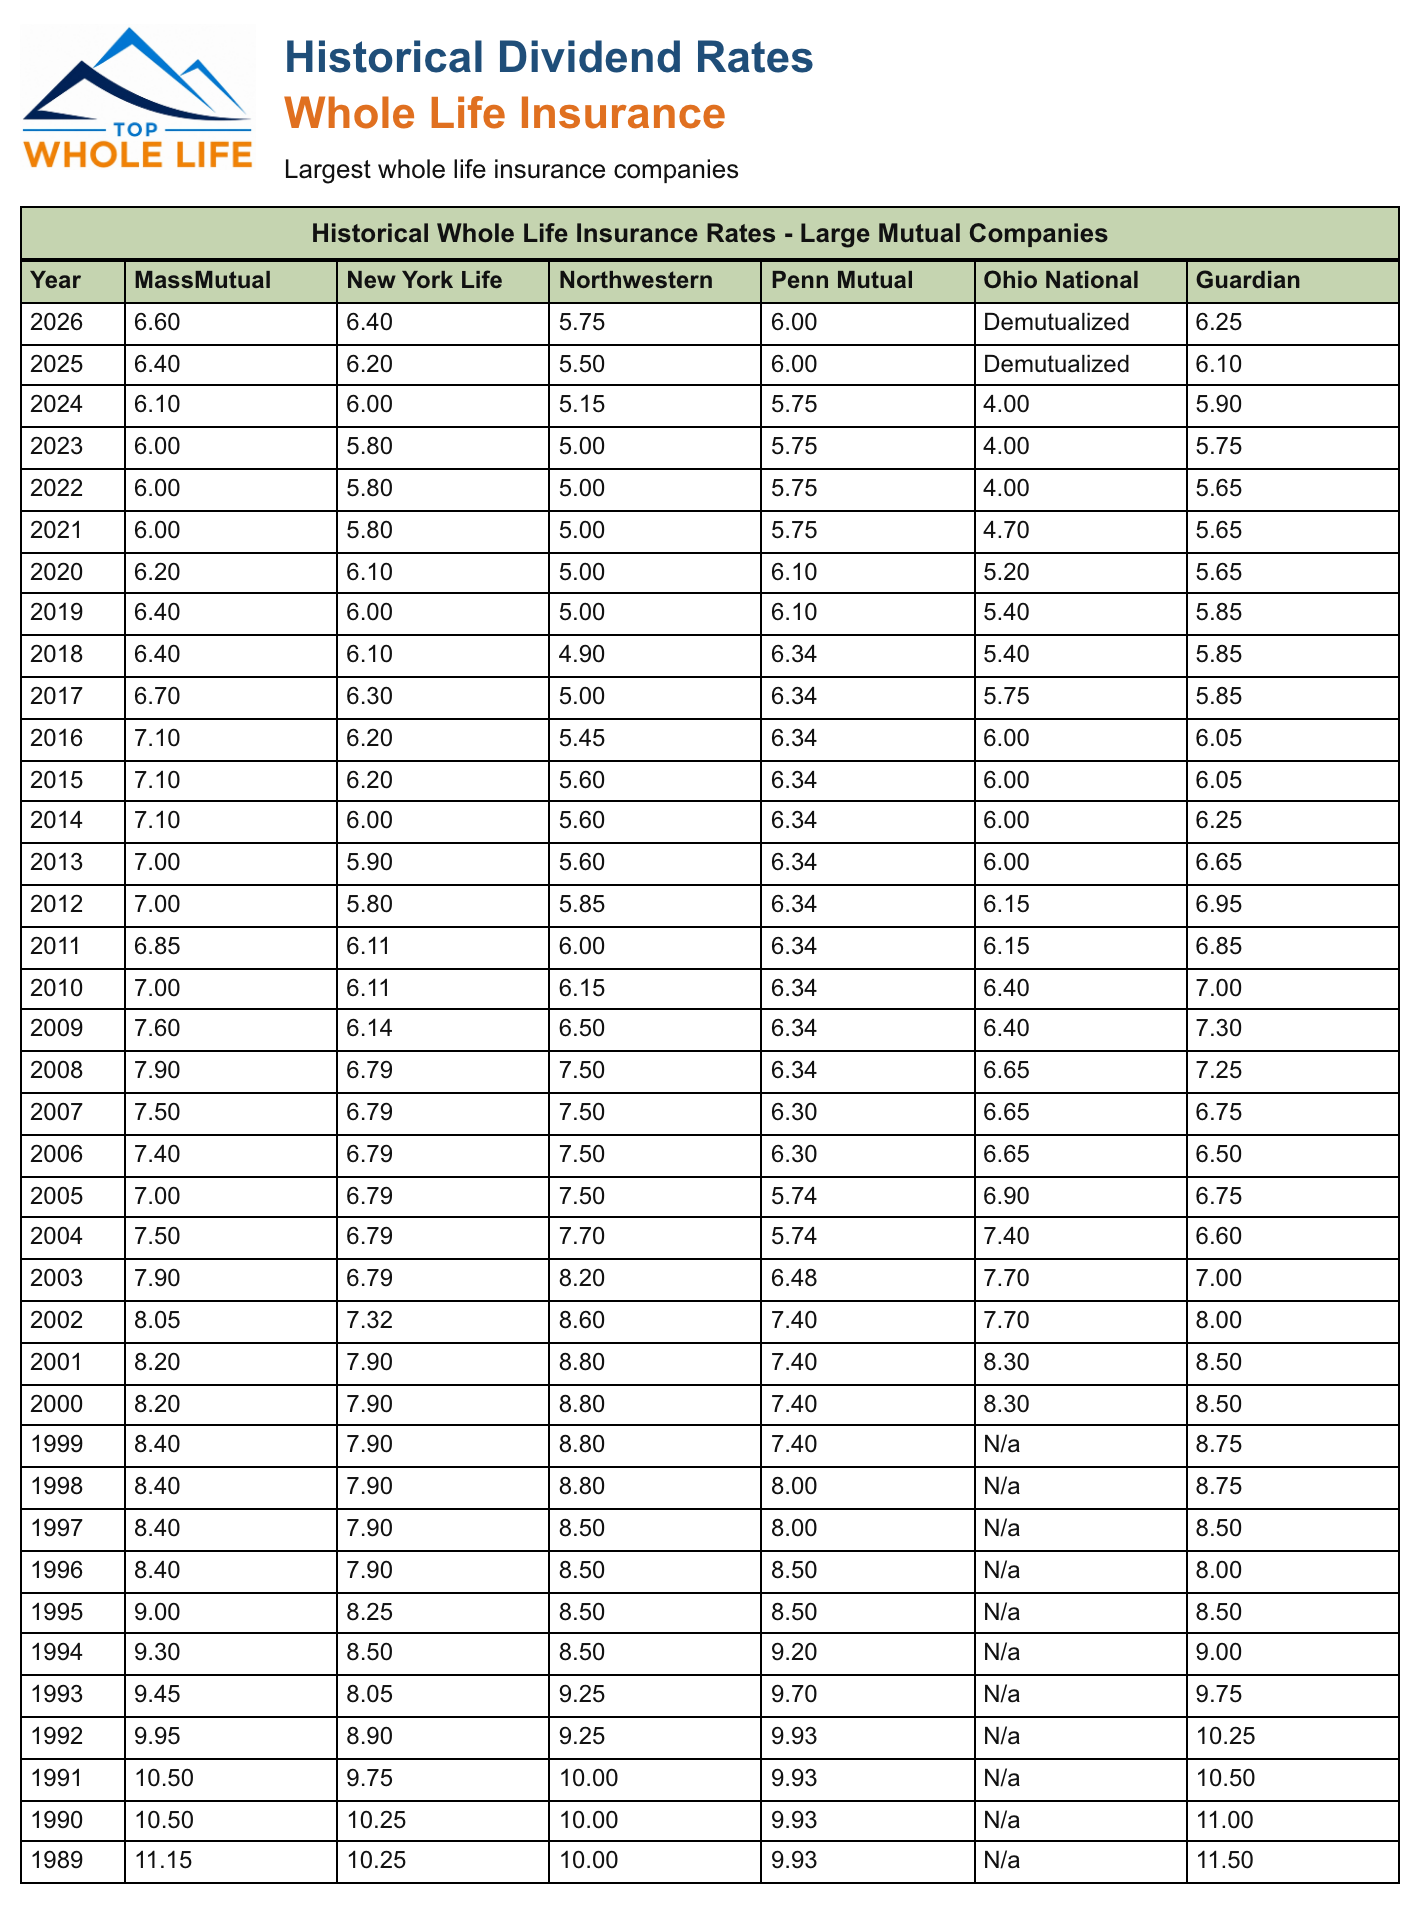
2026: 6.60% DIR (+20 bps vs. 2025) and about $2.9 billion total payout. The 2021–2023 floor was 6.00%. The full series through 2026 is on whole life dividend rate history.
MassMutual can be illustrated as non-direct recognition (adjustable-rate loans) or direct recognition (fixed-rate loans). That choice changes loan-year cash value. Ask for both if you plan to borrow.
The closest peers on DIR are New York Life (6.40%) and Penn Mutual (6.00%). DIR is not cash-value rank — run the same design at our quote tool.
Products
Whole Life Legacy 100
Level premiums to age 100. Usually the lowest premium in the Legacy lineup for a given face amount.
Whole Life Legacy 65
Guaranteed paid-up at age 65. Common when the story is retirement income. Related: whole life insurance in your 30s.
Whole Life Legacy 20 / 15 / 12 / 10 Pay
Limited pay designs. Shorter pay windows build cash value faster and cost more per year. The 15, 12, and 10 pay are often used for children or a defined working-years budget. Related: whole life in your 40s.
Whole Life Legacy HECV
High early cash value — often ~90% of first-year premium in cash. Used in business insurance. Lowest commission in the suite, so many agents never show it. Details: high early cash value whole life.
Survivor Whole Life 20 Pay
Second-to-die coverage on two lives. Pays at the second death. Estate and legacy planning, not income replacement on the first death.
Convertible term (Vantage)
If you are not ready for whole life, MassMutual’s Vantage term (10, 15, 20, 25, 30, and annually renewable) can convert later. An extended conversion period is a paid option on several terms. ART is the cheapest bridge if you expect to convert in the first few years.
Coverpath
Coverpath was MassMutual’s digital apply path for some term and Legacy whole life — not a different product. The public site now 301s to MassMutual’s account dashboard. Do not use it to start a new case. Details: Coverpath by MassMutual review.
Underwriting
MassMutual is stricter than average. Average-or-better health usually clears. Impaired-risk cases often illustrate better at Foresters or Penn Mutual.
Classes (best to weaker): Ultra Preferred, Select Preferred, Standard, Select Preferred Tobacco, Tobacco.
Get a whole life quote. We are not MassMutual agents. This is an independent review.
MassMutual account and payments
A policyowner account lets you see loans, beneficiaries, 1099s, cash value, and bills, and change address or payment method.
You cannot combine several MassMutual policies into one payment. Pay each policy, or save banking details and set recurring drafts.
Guest pay works on MassMutual.com under Billing and Payments without an account. Create the account anyway if you want paperless billing and stored bank information.
To register you typically need a phone number and email. Corporations and trusts need a TIN and policy number.
Bottom line
MassMutual is the first mutual we illustrate for cash-value whole life. Still compare the same pay period to New York Life, Penn Mutual, and Guardian. Rank the winner on top whole life companies for cash value.