New York Life Whole Life Insurance Review (2026)

2026 verdict: New York Life is a mutual you can trust to pay claims. It is one of four U.S. life insurers still carrying the highest marks from A.M. Best, Fitch, Moody’s, and S&P. The 2026 dividend interest rate is 6.40% on a record $2.8 billion payout — the 172nd consecutive year. It is a strong pick for lifetime protection and conservative cash value. It is not always the strongest illustration versus MassMutual or Guardian, and you usually buy it through a New York Life career agent, not an independent broker.
Who it is for: buyers who want a household-name mutual, Custom Whole Life limited-pay designs, or AARP-branded New York Life coverage at 50+. See our AARP life insurance review if that is the product in front of you.
Who should skip or compare first: shoppers who want the highest cash-value illustration, an independent agent who can place several mutuals, or a non-direct-recognition loan design. Start with the top whole life companies for cash value and get a whole life quote.
New York Life has issued policies since 1845. It is policyholder-owned. Year-end 2025 results (published 2026) show $34.7 billion surplus including the asset valuation reserve, $892 billion in assets under management, and about $1.26 trillion of individual life insurance in force. Dividends are not guaranteed.
New York Life products
The company sells term, whole life, universal life, and variable universal life. This review is about participating whole life. Universal life does build cash value (interest-credited or index/separate-account, depending on the contract). It is not the same product as whole life and is not a substitute for a dividend-paying mutual design.
Term (convertible)
Yearly renewable and level-premium convertible term can make sense as a bridge. You can convert many New York Life term policies to permanent coverage. Conversion credits, when available, are usually richest in the first five years — ask the agent to apply them if you convert.
Whole life (pay to 100 / 121)
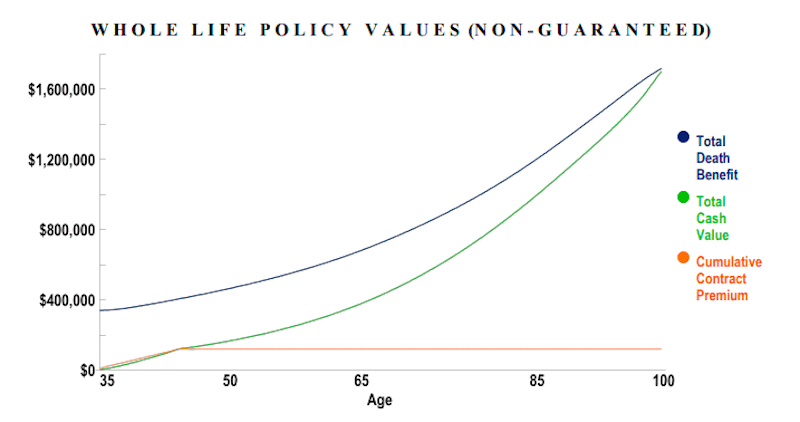
Level-premium participating whole life. Premiums stay level. Cash value and the death benefit are contractually guaranteed; dividends can buy paid-up additions on top.
Custom Whole Life
The limited-pay version. Premiums can be set to vanish at a chosen age (commonly between childhood and the mid-70s). Once paid up, the policy stays in force. This is the design most cash-value buyers compare. Related: limited pay whole life insurance.
Minimum face amounts are typically $25,000 on standard whole life and $50,000 on Custom Whole Life and juvenile cases, with higher minima at the better underwriting classes. Confirm the current band with an illustration — bands change.
Other permanent products
Variable universal and universal life sit in the “adjustable lifetime” family. Use them only if you specifically want flexible premiums or market-linked cash value. If the job is guaranteed premium, guaranteed cash value, and a dividend, stay on whole life. Background: what is whole life insurance.
Underwriting classes
New York Life prices from best to weaker classes along these lines (names can vary by product):
- Select Preferred
- Preferred
- Preferred II
- Non-smoker
- Select Standard
- Juvenile (typically ages 0–17)
- Non-smoker / standard special classes for some juvenile ages
Class plus face amount sets the premium. If you can afford whole life insurance, get two illustrations — New York Life and at least one other mutual — before you lock a class.
What a New York Life whole life policy actually does
- Guaranteed death benefit and level premiums
- Tax-deferred cash value; you can borrow against it
- Eligible for annual dividends (not guaranteed)
- Riders for living benefits, disability, and family coverage
That is standard participating whole life. The difference versus peers is the illustration, the loan/recognition rules, and how you buy it — not a unique “passive income” story.
Riders (common menu)
Availability depends on product, state, and underwriting. Treat this as a menu, not a promise that every rider is free or in force on every policy.
Often included or low-friction
- Living Benefit / accelerated death benefit — access part of the death benefit if a physician certifies a qualifying terminal illness (often 12 months or less).
- Spouse’s Paid-Up Insurance Purchase Option — after a death claim, the surviving spouse may use proceeds to buy a paid-up policy on their own life.
- Insurance Exchange — transfer the policy to another party; the rider may be free, the transfer itself is not.
Usually paid
- Accidental death benefit
- Children’s term / child’s protection (keeps a child insurable into young adulthood)
- Chronic care / chronic illness acceleration
- Disability waiver of premium
- Payer protection (when the payer is not the insured)
- Dividend option term, level-premium convertible term, and yearly convertible term (extra term that can later convert)
- Option to purchase paid-up additions (front-loads cash value)
- Policy purchase option (add coverage later without a new exam)
Financial strength (as of late 2025 / 2026)
New York Life’s own 2025 report-to-policyowners commentary (ratings as of 10/28/2025) lists:
| Agency | Rating | Note |
|---|---|---|
| A.M. Best | A++ (Superior) | Highest; affirmed 2026, stable outlook |
| Fitch | AAA | Highest |
| Moody’s | Aa1 | Second-highest; U.S. life insurers are often capped vs. the sovereign |
| S&P | AA+ | Highest currently awarded to a U.S. life insurer |
That is claims-paying strength. It is not a reason to skip a side-by-side illustration.
Year-end 2025 (published 2026): $3.6 billion operating earnings, $34.7 billion surplus including AVR, $2.8 billion dividend declared for 2026, $892 billion AUM. Older copy on this page that said “$27 million surplus” was a units error — the figure is in the tens of billions.
Dividends
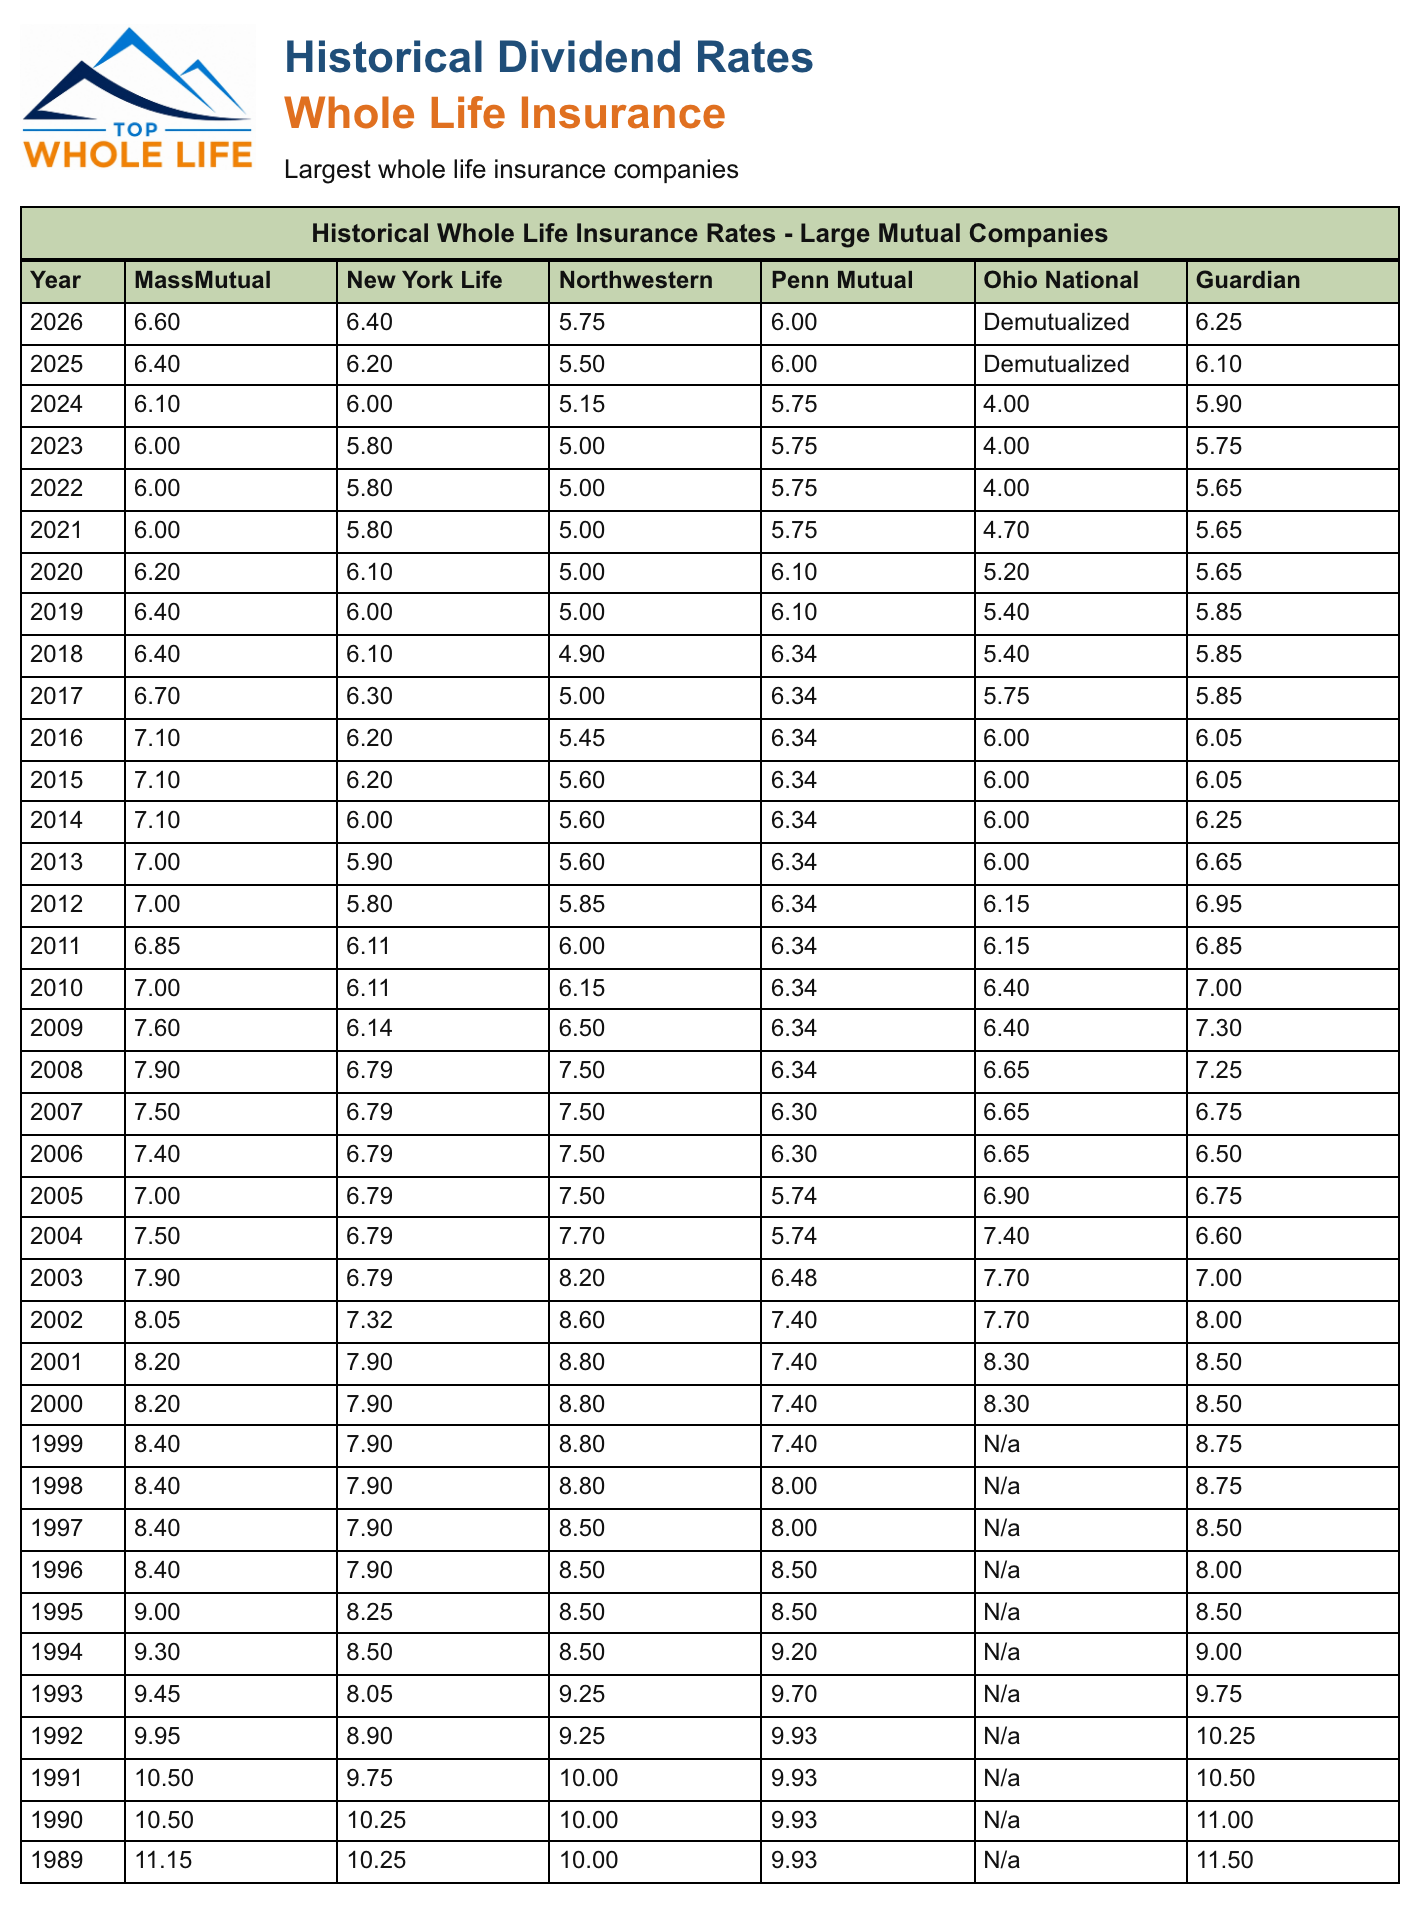
The 2026 dividend interest rate is 6.40% (+20 bps vs. 2025). The declared payout is about $2.8 billion. The floor in the last decade was 5.80% (2012, then 2021–2023).
Do not use a table that stops in 2021. The full year-by-year series lives on whole life dividend rate history (2026 DIR 6.40%; 5-year average about 6.04%). MassMutual still prints a higher 2026 DIR at 6.60%. DIR is not the same as cash-value performance — compare illustrations.
Drawbacks
New York Life is a career-agency company. Independent agents cannot freely shop every New York Life case the way they can shop MassMutual or Penn Mutual. Smaller premium cases are especially likely to stay inside the New York Life agency channel. If you already have an independent broker you trust, that friction is real.
AARP-branded policies are also New York Life, but they are a different product set (simplified issue, membership, lower face bands). Do not treat an AARP mailer as a Custom Whole Life illustration.
Bottom line
New York Life belongs in the first conversation for participating whole life. Compare it on the same design (pay period, direct vs. non-direct recognition, paid-up additions) against MassMutual and Guardian. Then get a whole life quote or call (209) 867-5433.
Top Whole Life is an independent marketing firm. We do not work for New York Life.