Guardian Whole Life Insurance Review (2026)
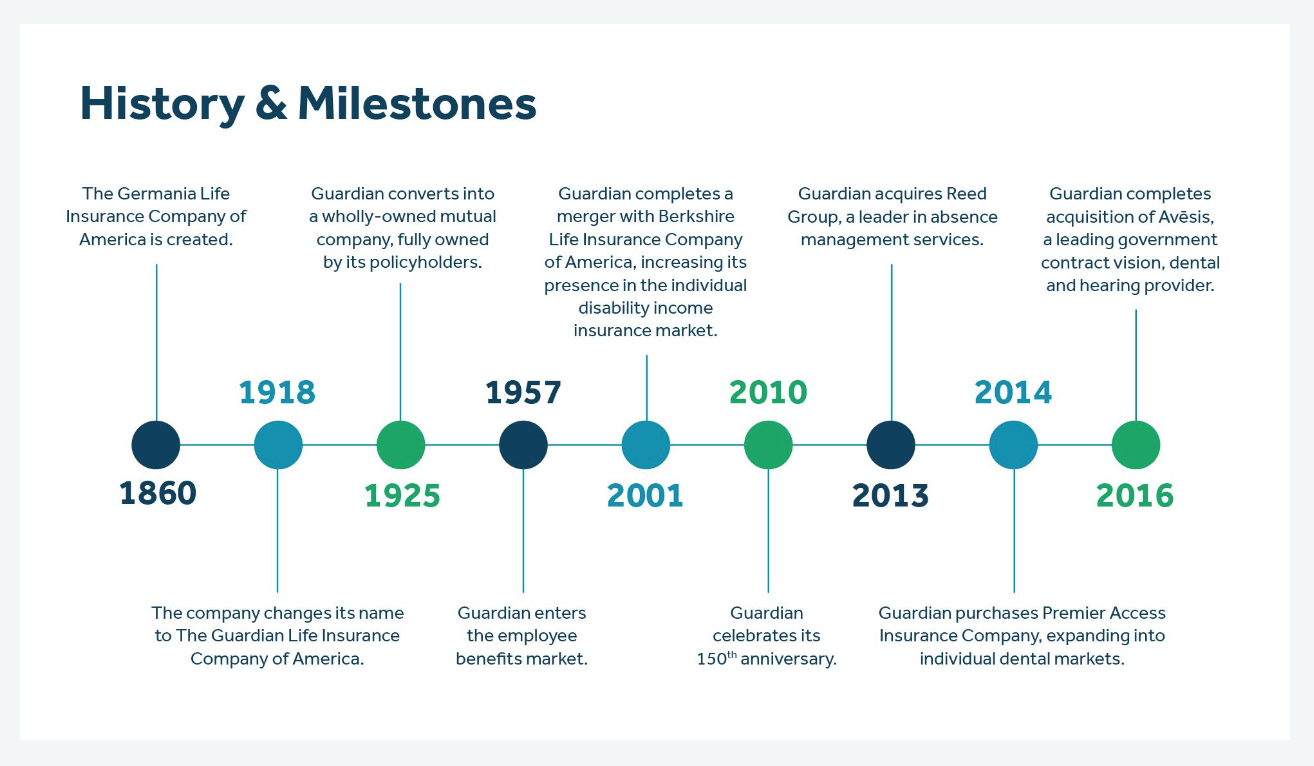
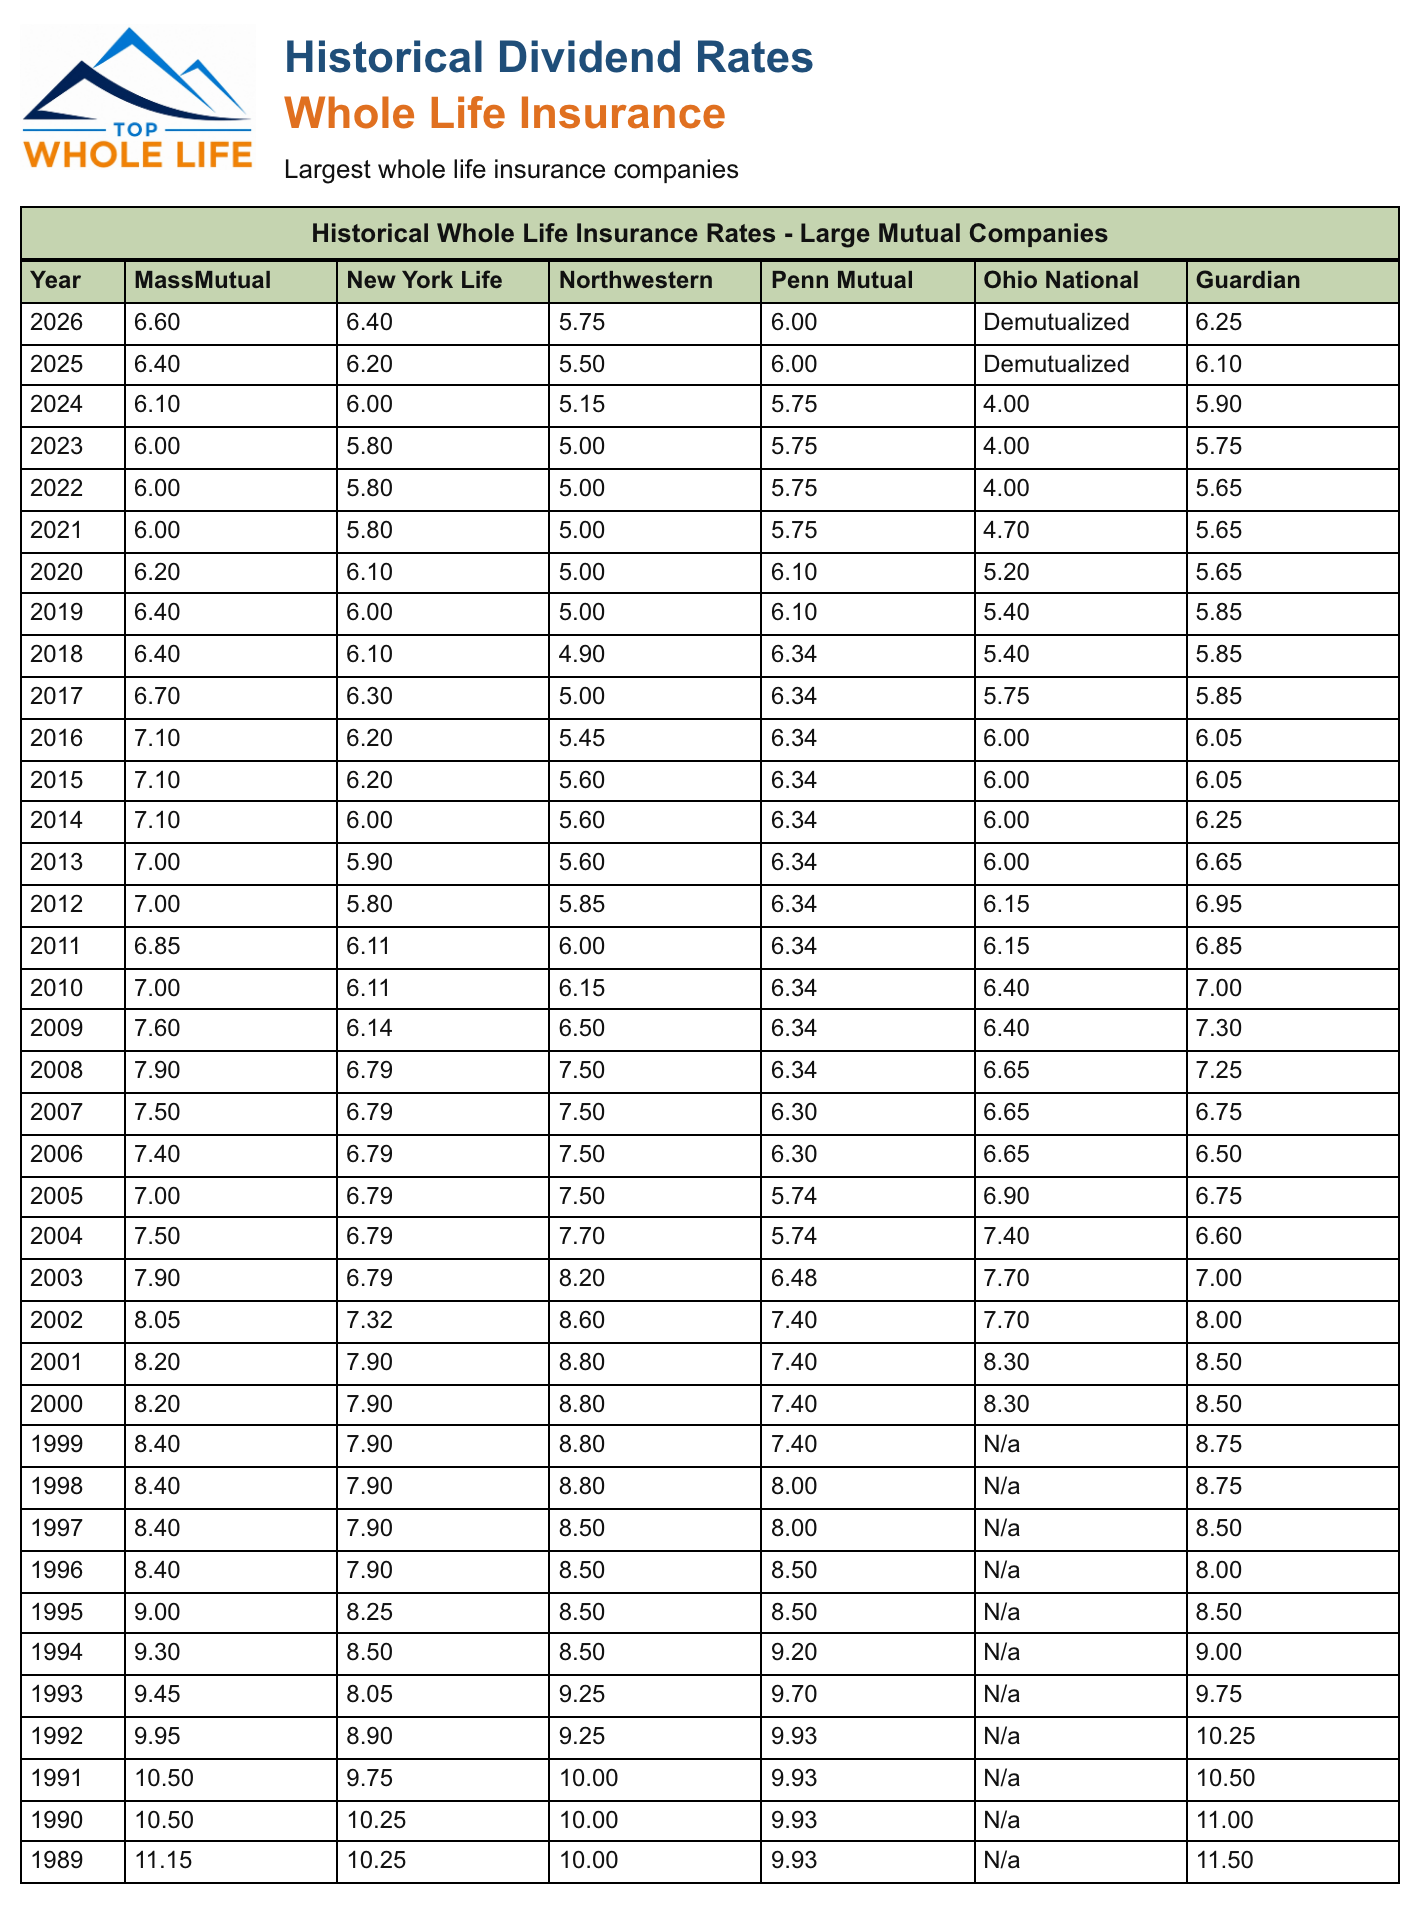
2026 verdict: Guardian is a top-tier mutual again. The 2026 dividend interest rate is 6.25% (+15 bps vs. 2025) on a record $1.7 billion payout. A.M. Best is A++. Cash-value illustrations are competitive but often still trail MassMutual. Buy Guardian when the design, underwriting, or advisor fit wins — not because a 2022 article said the dividend was “always dropping.”
If you only want a quote: get a whole life quote.
Who it is for
Buyers who want participating whole life from a New York mutual with strong disability and worksite businesses on the side. Level-pay, 10-pay, 20-pay, and second-to-die (EstateGuard) are the usual whole life menu.
Who should compare first: anyone whose only metric is illustrated cash value or DIR. MassMutual is 6.60%; New York Life is 6.40%. Full series: whole life dividend rate history.
The good
Guardian is a mutual. Policyowners are eligible for dividends when declared. Performance still comes from investments, claims, and expenses — the same three levers every mutual uses.
| Agency | Rating |
|---|---|
| A.M. Best | A++ (Superior) |
| S&P | AA+ (Very Strong) |
| Moody's | Aa2 (Excellent) |
| Fitch | AA+ (Very Strong) |
Fortune 500 placement has sat in the mid-200s in recent lists (about #252 on one compiled 2025 ranking). That is scale, not a product score. Current capital and in-force figures change every year — use Guardian’s latest fact sheet, not 2015 “highest-earning year” or 2021 AUM copy.
The less good
The DIR did fall from the mid-6%s (2012–2014) to a 5.65% floor in 2020–2022. That stretch is over. 2023–2026 climbed to 6.25%. Saying “the dividend is constantly dropping” is no longer accurate.
Guardian’s career-agency network is smaller than New York Life’s. You do not need a local office to buy, but you may not have a Guardian storefront on the corner.
Products
All Guardian participating whole life shares the usual guarantees: death benefit, cash value, level premiums, dividends not guaranteed. Whole life is the company’s core individual life line.
Level premium whole life — pay to 95, 99, or 120. Longer pay = more death benefit per premium dollar.
Limited payment whole life — typically 10-pay and 20-pay. Related: limited pay whole life insurance.
EstateGuard whole life — second-to-die. Legacy and estate liquidity, not first-death income replacement.
Riders
Confirm on the illustration. Common options: waiver of premium, guaranteed insurability, paid-up additions, renewable term, accidental death, DuoGuard (beneficiary purchase right), simplified insurability, and enhanced accelerated benefits (terminal / some chronic).
Index Participation Feature (IPF) allocates some paid-up-addition cash value toward S&P 500-linked crediting with a cap and floor. It is optional complexity, not “Guardian becomes IUL.” Ask for a with/without IPF illustration. Rider overview: what are life insurance riders.
Bottom line
Guardian belongs in the first conversation with MassMutual, New York Life, and Penn Mutual. Rank the illustration on top whole life companies for cash value. For participating mechanics, see participating whole life insurance.