Whole Life Dividend Option Change Checklist
A whole life dividend option change is one of the quietest ways to alter a policy—and one of the easiest to do from a phone call without seeing the math.
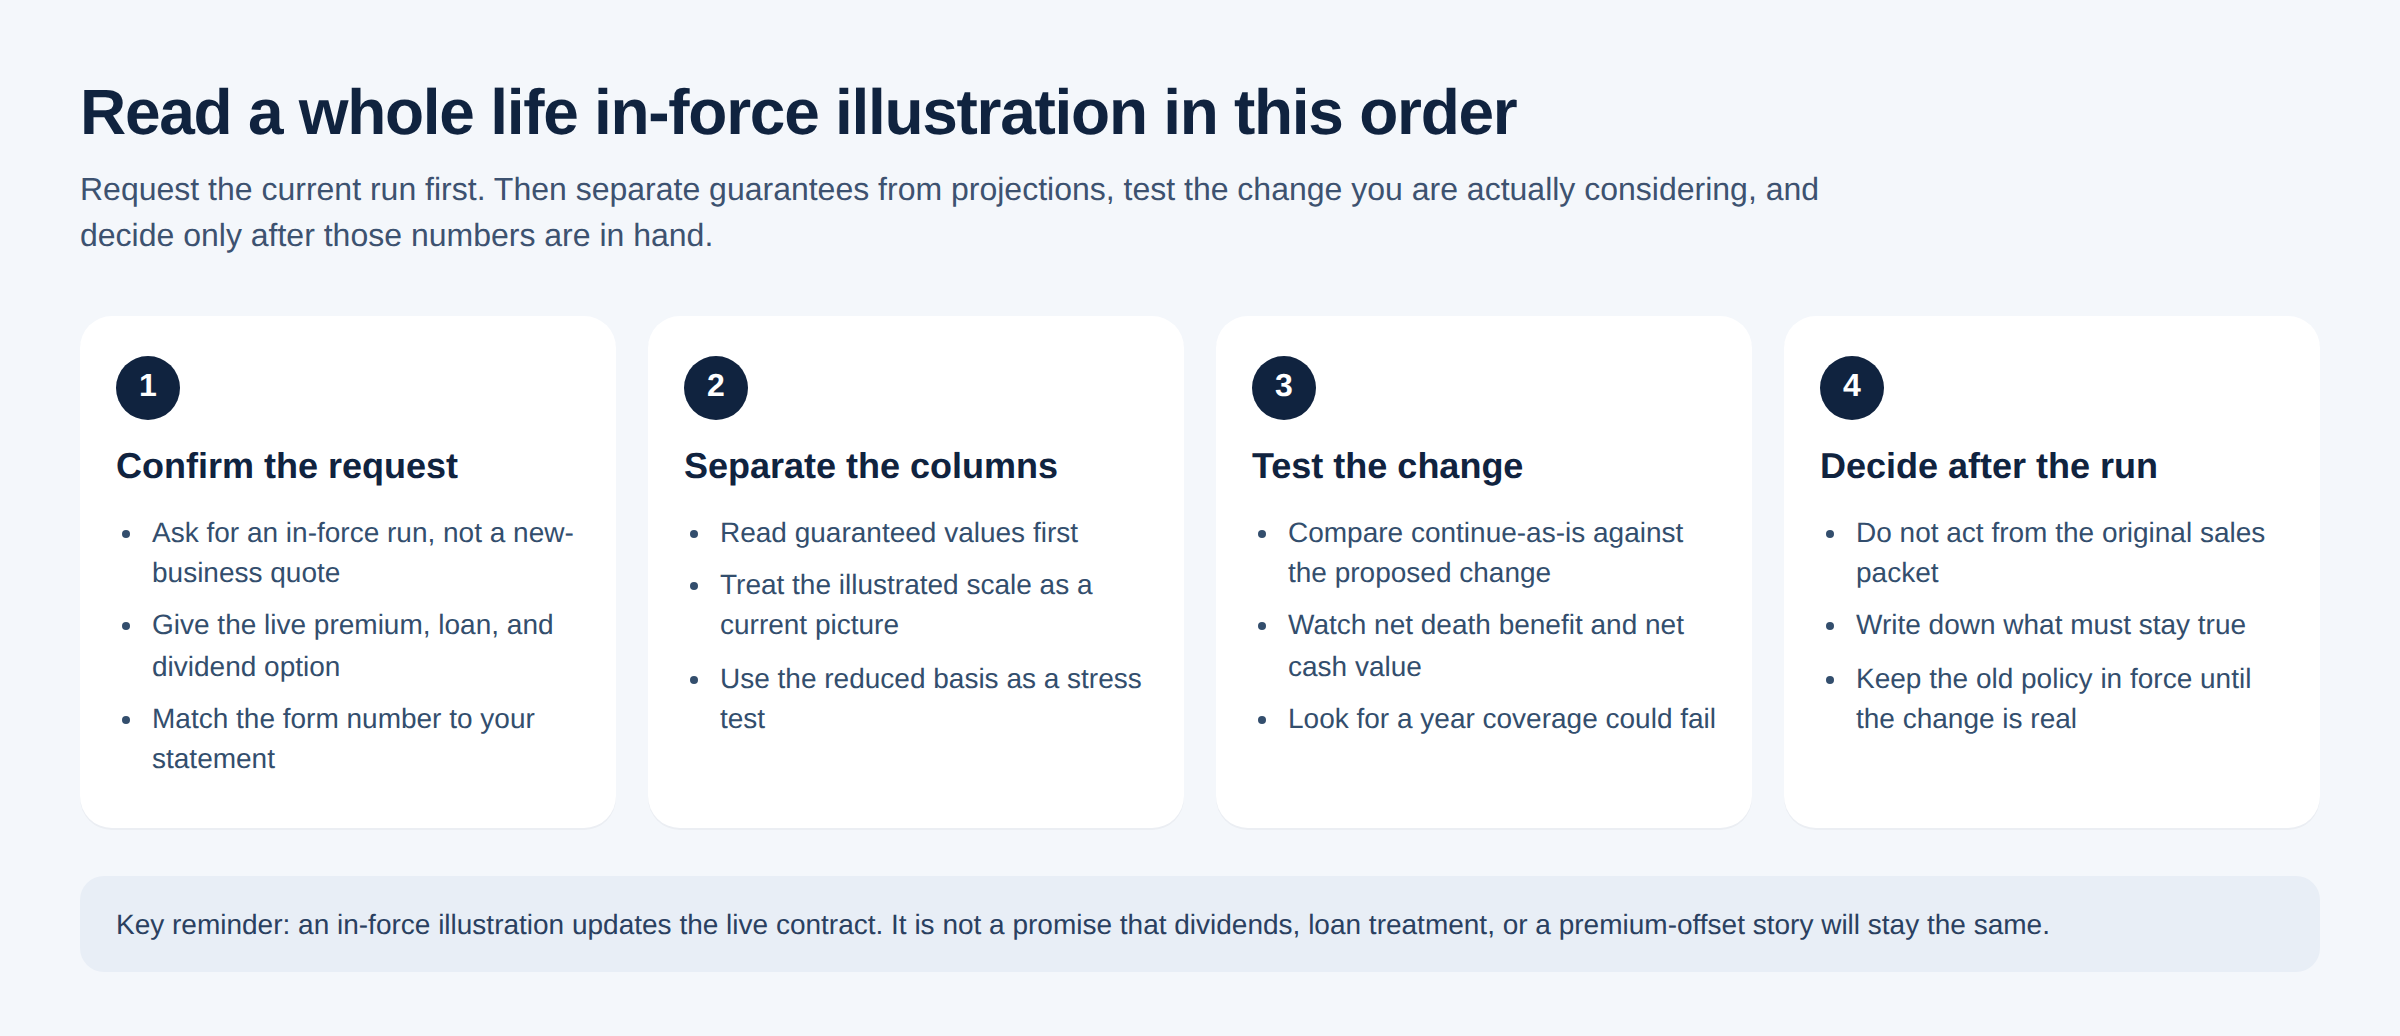
Dividends are not guaranteed. The option you elect (paid-up additions, reduce premiums, accumulate at interest, cash, or another carrier menu item) changes how non-guaranteed dollars are applied. Before you switch, you want the live election, a current in-force illustration, and a clear reading of the guaranteed floor.
Top Whole Life's in-force illustration guide is the companion document for the projection. This checklist is the decision hygiene before you ask the carrier to change the election.
The NAIC consumer life insurance page is blunt about cash-value products: non-guaranteed elements can change. Treat any "this will pay for itself" story as a scenario, not a promise.
Change the dividend option only after you can name the current election, the illustrated effect, and what still holds on the guaranteed basis.
Confirm what you actually have today
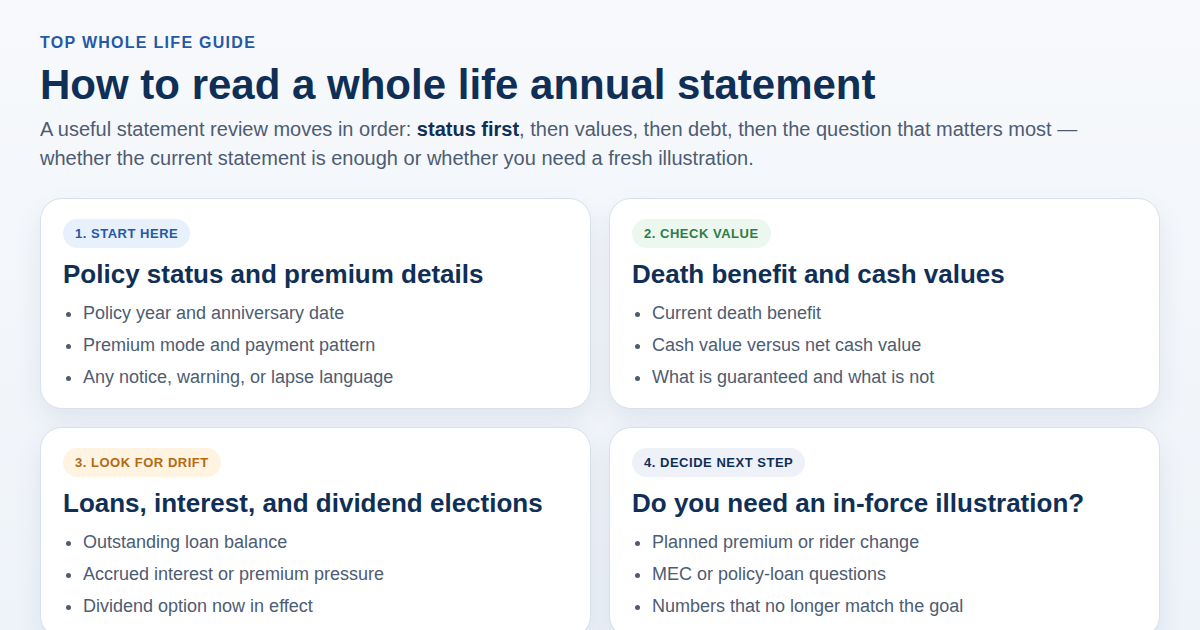
Pull the latest annual statement and policy pages. Write down:
- current dividend option in force
- whether paid-up additions (PUAs) are buying extra paid-up insurance
- whether premiums are already being offset or reduced by dividends
- loan balance and loan interest treatment, if any
- whether a rider depends on a particular dividend application
If the statement and the original sales illustration disagree, believe the live statement—then request an in-force run before changing anything. See the annual statement guide.
Match the option to the job
| If your goal is… | Option people often consider | What to verify first |
|---|---|---|
| Grow long-term death benefit / cash value | Paid-up additions | Illustrated PUA purchases vs guaranteed columns |
| Lower out-of-pocket premium | Reduce premiums / premium offset | Whether offset still works if dividends fall |
| Liquidity outside the policy | Cash dividends | Tax and cash-value tradeoffs with a professional |
| Park dividends for later decisions | Accumulate at interest (if offered) | Crediting rate and how withdrawals interact |
For a plain-English PUA primer, use what paid-up additions are. Do not treat blog language as a substitute for the carrier's option definitions on your form.
Request the right in-force illustration
Ask the carrier or servicing agent for an in-force illustration that shows:
- continue as-is on the current dividend option
- the proposed new option with the same premium pattern
- guaranteed, current-scale, and reduced/midpoint bases when the illustration rules require them
New York's illustration guidance and the broader NAIC model family emphasize that non-guaranteed elements are not guarantees. If the new option only "works" on the illustrated scale, write that down before you sign a request form.
Checklist before you submit the change
- I can name today's dividend option from the statement.
- I have a current in-force illustration for both options.
- I reviewed guaranteed values, not only year-20 illustrated cash value.
- I checked loan behavior if a loan exists or is planned.
- I asked whether the change is reversible and how long processing takes.
- I am not relying on "vanish" language that implies premiums disappear as a guarantee.
- If MEC limits or large dump-ins are involved, I asked how the new option interacts.
When not to change yet
Wait if:
- you only have the original sales packet
- someone is pitching premium offset without a current run
- a loan is already stressing the contract and nobody has illustrated the combination
- you are mid-replacement or 1035 and the surviving contract is still unclear
Questions for the carrier
- What is my dividend option on the live policy today?
- What changes on the guaranteed basis if I switch?
- What has to stay true on the illustrated scale for the new plan to hold?
- How are loans treated under each option on this form?
- When does the new election take effect relative to the next dividend anniversary?
If you want a fresh comparison after you understand the live contract, use the whole life quote form and compare it against the current policy instead of assuming the first available change is best.
This article is general education only. Dividend options, illustration rules, and tax treatment vary by insurer and state. Confirm the live form and a current illustration with your carrier or a licensed professional before changing elections.