Banner Life Insurance Review (2026)
2026 verdict: Banner Life, part of Legal & General America, is a term specialist. In New York the sister company is William Penn Life Insurance Company of New York. If you want level term and you are healthy, Banner is often worth a quote. If you want participating whole life, this is the wrong company. Leave for MassMutual or the top whole life companies for cash value.
Get a whole life quote for permanent coverage. For term, start at cheap term first.
Who it is for
| You want | Banner / William Penn | A whole life mutual |
|---|---|---|
| Level term for a mortgage, income years, or until kids are grown | Often yes, if you qualify | Usually more premium than you need for a temporary need |
| Coverage you can convert later | Ask what product conversion lands in. Conversion is not the same as a MassMutual paid-up-additions policy. | Buy whole life now if that is the contract you actually want |
| Cash value, dividends, limited pay | No. That is not this shelf. | Yes. Start with the cash-value list. |
| You live in New York | William Penn, not the Banner contract used in other states | Mutual availability depends on the carrier |
Who should skip: buyers who searched “Banner” because they want cash value. The rates that make Banner look cheap are term rates.
Company
Banner has sold life insurance in the United States since 1981 under the Legal & General America companies. What matters for a quote is the product, not the holding-company headline: Banner is staffed and priced as a term writer.
A.M. Best ratings on the Legal & General America life companies have typically been in the A+ range. Confirm the rating on the illustration you are about to sign. Do not treat a review’s rating line as the policy.
How to read a Banner term quote
Term is the right tool when the need ends. Price is the premium for the guarantee period (10, 15, 20, 25, 30 years are the usual shelves — your state and age decide which exist). After the level period, renewal premiums jump. Plan on the coverage ending, or on converting or replacing it before that date, not on paying the renewal.
Three checks before you bind:
- Issuer and state. Banner outside New York. William Penn in New York. The application should match where you live.
- Conversion window and destination. Get the deadline in writing, and the name of the permanent product you would convert into. If that product is not the whole life design you want, do not count conversion as your permanent plan.
- Health class. The cheap advertised rate is usually Preferred or better. A standard or tobacco class can erase the gap versus another carrier. Compare the class you were actually approved for.
The difference between a temporary need and a lifetime contract is on whole life vs term.
What Banner will not do for a cash-value buyer
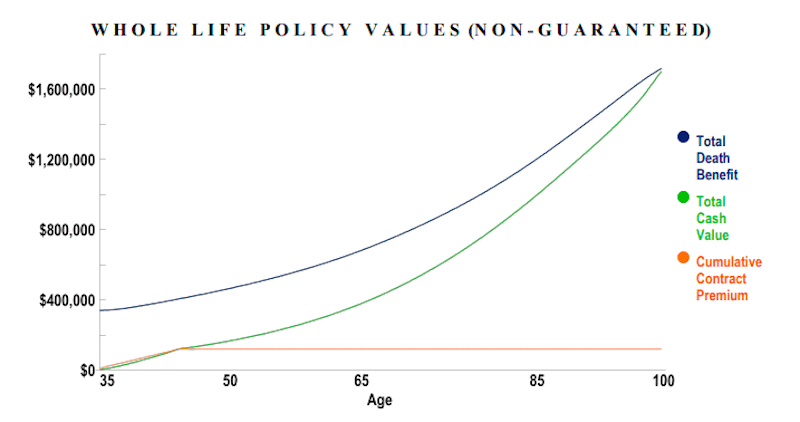
You will not get a mutual-style dividend or a paid-up-additions illustration here. If the goal is cash value you can borrow against under a guaranteed premium, quote MassMutual and at least one other mutual on the same face amount. Get a whole life quote.
Bottom line
Use Banner (or William Penn in New York) when the job is term and the approved rate is competitive. Use a mutual when the job is whole life. Do not buy the term company because the name came up next to a permanent-insurance search.